

Business insurance · Commercial auto · California
Commercial Auto Insurance in California for Work Trucks, Vans and Company Cars
A pickup that carries tools to job sites, or a van that runs deliveries, usually belongs on a business auto policy instead of the family car policy. Commercial auto insurance covers the vehicles your business owns and can reach rentals and employees' own cars on company errands. We quote it for small businesses across California from our office in Valencia.
- Licensed in CA · #0D44425
- Free quotes, no obligation
- Call-back usually within the hour


At a glance
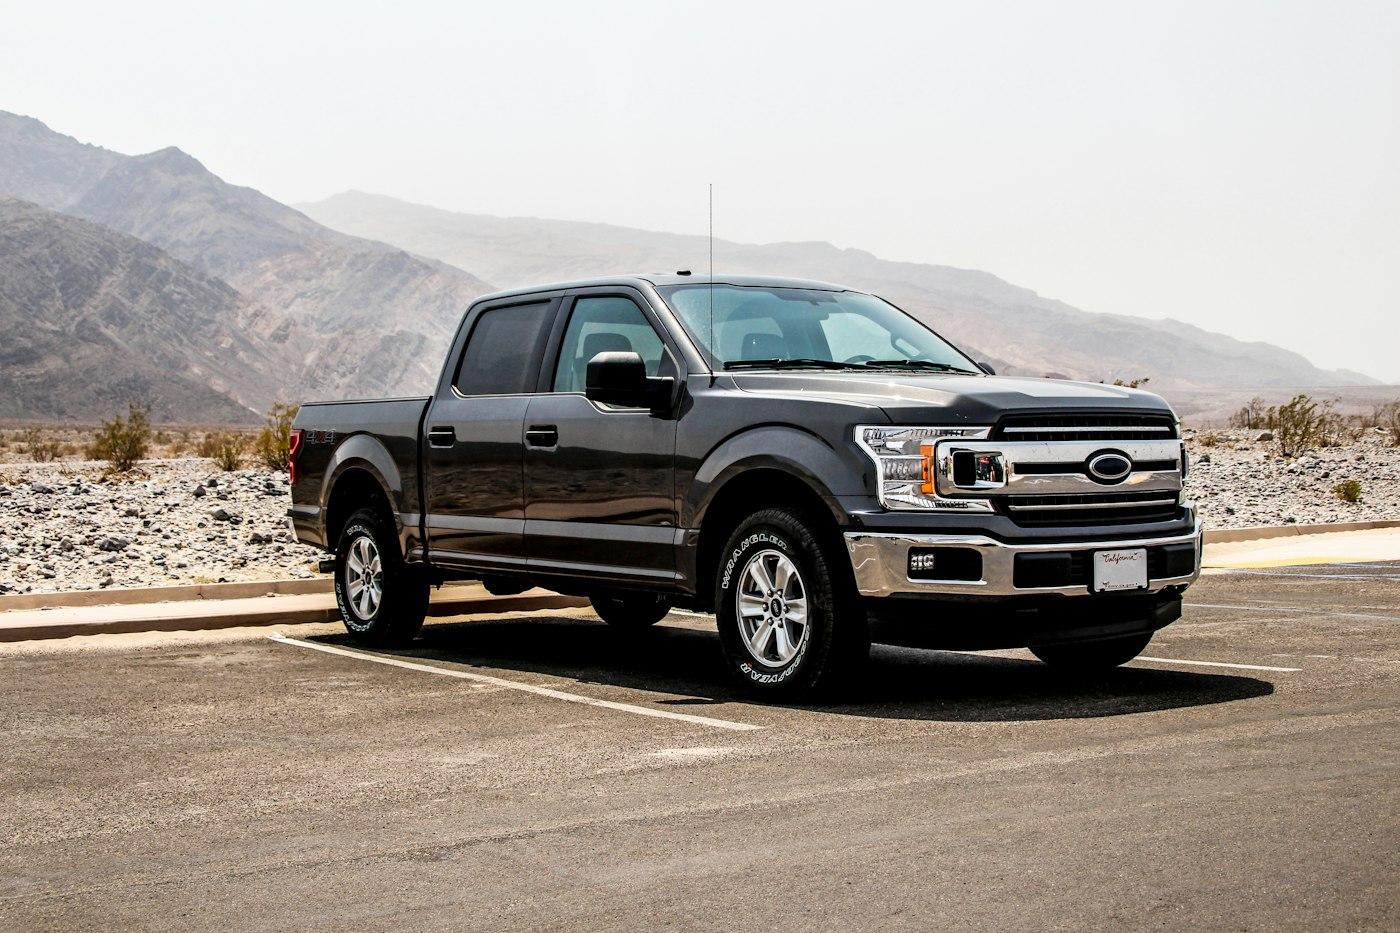
- The California Department of Insurance (CDI) has said personal auto policies do not typically cover vehicles used for commercial purposes.
- Business auto policies usually carry one combined single limit, and the CDI lists $500,000 and $1,000,000 as common choices.
- Hired and non-owned auto covers the business's liability when employees drive their own or rented vehicles for work.
- Business trucks with two or more axles and a gross vehicle weight rating (GVWR) over 10,000 pounds generally need a DMV Motor Carrier Permit and at least a $750,000 combined single limit.
- Carriers we quote for business vehicles include NEXT and Travelers.
Commercial auto
Coverage options, in plain English
What each part of a policy can pay for. The exact coverage depends on the policy and the carrier, and we go through it with you before you buy.
Not sure which parts you need?
Tell us what you're insuring and we'll explain the trade-offs before you sign.
Get my free quoteLiability
Pays for injuries and damage your drivers cause to others, plus your legal defense.
Collision and comprehensive
Repairs or replaces your own vehicles after a crash, theft, fire or vandalism, minus your deductible.
Hired and non-owned auto
Liability for the business when employees drive their own cars for work or when you rent a vehicle.
Uninsured and underinsured motorist
Pays for injuries to people in your vehicle when the at-fault driver has little or no insurance.
Medical payments
Helps with medical bills for people riding in your vehicle, regardless of fault, up to a set limit.
Rental reimbursement and towing
Optional help while a covered vehicle is in the shop.
On this page8
When do you need commercial auto instead of a personal policy?
Short answer
Usually when a vehicle is titled to the business, driven by employees, used to haul tools or goods, or used for paid trips and deliveries. Personal policies are written for personal driving, and the CDI has said they don't typically cover vehicles used for commercial purposes.
- Who owns it: a vehicle titled to your LLC or corporation generally needs a policy issued to the business.
- Who drives it: employees behind the wheel make it a business exposure, even with the title in your name.
- What it carries or tows: tools, materials, inventory or a trailer point to business use.
- How it earns money: deliveries, hauling for customers and carrying people for a fee are commercial use.
Some personal carriers will rate a car for light business use, like a sales rep visiting clients, so occasional work driving doesn't always mean a new policy. Trouble starts when the use listed on the policy and the use on the road don't match. Our California car insurance page covers the family side.
What does a commercial auto policy cover?
Short answer
A business auto policy can cover liability for injuries and property damage your drivers cause, collision and comprehensive damage to your own vehicles, medical payments and uninsured motorist protection. The business is the named insured, and coverage can follow employees who drive with permission.
Many business auto policies use numbered "covered auto symbols" to show which vehicles each coverage applies to. Symbol 1 means any auto, symbol 7 means only the vehicles listed, and symbols 8 and 9 add hired and non-owned autos. Two policies with the same limits can cover very different vehicles, so we compare symbols, not just price.
What it usually leaves out
- Tools and equipment in the truck need their own coverage; see contractor insurance.
- Injuries to your own employees are usually a workers' compensation claim, even in a crash.
- Customers' goods you haul need cargo coverage.
- A customer who slips at your shop belongs on general liability.
How much liability coverage do contracts ask for?
Short answer
Many contracts, leases and permits set a minimum auto liability limit, usually written as one combined single limit per accident. The CDI lists $500,000 and $1,000,000 as common commercial limits, far above California's 30/60/15 minimum for a private car.
Where auto liability numbers come from
California's minimum for most cars
- What it usually looks like
- 30/60/15 split limits; see California's minimum car insurance requirements
Common commercial limits, per the CDI
- What it usually looks like
- $500,000 or $1,000,000 combined single limit
Motor Carrier Permit holders
- What it usually looks like
- At least $750,000, or $300,000 for carriers that run only vehicles under 10,000 pounds GVWR and haul no hazardous loads (Vehicle Code section 34631.5)
General contractors, landlords and public agencies
- What it usually looks like
- Whatever the contract says, often with additional insured wording
| Source of the requirement | What it usually looks like |
|---|---|
| California's minimum for most cars | 30/60/15 split limits; see California's minimum car insurance requirements |
| Common commercial limits, per the CDI | $500,000 or $1,000,000 combined single limit |
| Motor Carrier Permit holders | At least $750,000, or $300,000 for carriers that run only vehicles under 10,000 pounds GVWR and haul no hazardous loads (Vehicle Code section 34631.5) |
| General contractors, landlords and public agencies | Whatever the contract says, often with additional insured wording |
A split limit like 30/60/15 caps payments per injured person and per accident, with a separate cap for property damage. A combined single limit is one amount for the whole accident. Send us a contract's insurance section before you sign so the quote matches it.
What is hired and non-owned auto coverage?
Short answer
Hired and non-owned auto (HNOA) covers your business's liability when someone drives a vehicle the business doesn't own for work, such as an employee's own car on an errand or a truck you rent. It pays other people for injuries and damage; it doesn't repair the car being driven.
Say your office manager takes her own SUV to the bank on McBean Parkway and rear-ends someone at a light. Her personal policy usually pays first, but the injured driver can sue your business too, and her limits may run out. HNOA is built for that gap.
NEXT sells HNOA as an add-on to its general liability policy. On a business auto policy it comes from symbols 8 and 9. It matters even for a business that owns no vehicles at all.
Quote your work vehicles
Send the vehicle list and any insurance terms from your contracts. On weekdays from 9 to 4, Brian or Dolores usually calls you back within the hour.
Do California work trucks need a Motor Carrier Permit?
Short answer
Some do. California requires a Motor Carrier Permit (MCP) from the DMV for business trucks with two or more axles and a GVWR over 10,000 pounds and for any vehicle that hauls other people's property for pay. The DMV checks liability and workers' comp insurance before it issues the permit.
- Heavy-duty pickups count. In a California Highway Patrol (CHP) example, a construction company's pickup rated at 10,500 pounds and towing a trailer needs an MCP.
- So can lighter trucks. A pool service pickup rated under 10,001 pounds needs one because the pool chemicals it hauls are hazardous materials.
- Any size, if you haul for hire. Delivering other companies' goods for pay makes you a for-hire carrier.
- The order of steps: a USDOT number from the Federal Motor Carrier Safety Administration, a CA number from the CHP, then the MCP from the DMV.
Running without a required MCP is a misdemeanor, and the truck can be impounded. The CHP's Motor Carrier of Property Permit FAQ (opens in a new tab) walks through real examples. For-hire and interstate trucking are specialty markets; tell us what you haul and we'll say plainly whether we can place it.
Check the door jamb
The GVWR is printed on the certification label on the driver's door edge or door frame. Heavy-duty pickups can be rated above 10,000 pounds, so read yours.
What affects the price of commercial auto insurance in California?
Short answer
The vehicles, the work they do, where they're parked, how far they travel, who drives them, and the limits and deductibles you choose. A landscaper's dump truck and a realtor's sedan are rated so differently that an average price says little.
- Vehicle type and weight: sedan, van, pickup, box truck or dump truck.
- Use and radius: service calls around the Santa Clarita Valley rate differently from daily runs up I-5 over the Grapevine to Bakersfield.
- Garaging ZIP code: where each vehicle sits at night.
- Drivers: each driver's record, age and experience.
Driver records weigh heavily on a business policy, and one driver with a serious violation can change the whole quote. The DMV's Employer Pull Notice program, mandatory for some commercial drivers, lets any employer enroll other drivers with their written consent and keep watch on their records.
How we quote commercial auto
- 1
Send the vehicles
VIN, GVWR, the name on each title, and where each one is parked.
- 2
Add the drivers
Names, license numbers and dates of birth for everyone who drives, part-timers included.
- 3
We compare carriers
We shop carriers such as NEXT and Travelers and lay out limits, symbols and deductibles side by side.
- 4
Sign and get proof
You e-sign, and we email ID cards and any certificates your customers ask for.
Mercury Insurance, one of the carriers we quote for family cars, also writes business auto in California. If your personal cars are already with Mercury, ask whether the work truck can join them. Our business insurance overview shows how auto fits with other policies, and Valley owners can start with business insurance in Santa Clarita.
Sources we used for this page (6)
- 1California Department of Insurance: Commercial Insurance Guide (opens in a new tab)insurance.ca.gov
- 2California Department of Insurance: April 10, 2020 release on personal auto policies and commercial use (opens in a new tab)insurance.ca.gov
- 3California Highway Patrol: Motor Carrier of Property Permit FAQ (opens in a new tab)chp.ca.gov
- 4California DMV: Motor Carrier Permit program (opens in a new tab)dmv.ca.gov
- 5California DMV: Employer Pull Notice program requirements (opens in a new tab)dmv.ca.gov
- 6California DMV: Report of Traffic Accident Occurring in California (SR-1) (opens in a new tab)dmv.ca.gov
Commercial auto
Carriers we can quote
We work with 30 insurance companies, so we can run your details with carriers like NEXT and Travelers, then show you the options side by side. Each carrier makes its own underwriting decision, so acceptance and final rates are up to them. We'll tell you which ones fit before we quote.
Not every carrier writes every property, vehicle or business. Final rates and eligibility are set by the insurance company.
Questions we hear a lot
Commercial auto: common questions
Short answers to what people ask us most. Anything else, call and ask Brian or Dolores.
Still have a question?
Talk to a licensed agent at the Valencia office.
(818) 909-7486Mon to Fri, 9 AM to 4 PM
Does commercial auto insurance cover the tools in my truck?
Usually not. A business auto policy covers the vehicle and your liability for driving it, not the tools, ladders, materials or equipment inside. Those go on an inland marine form, often called a tools or contractor's equipment policy, which follows the gear from the truck to the job site. Our contractor insurance page explains how it's set up.
Do I need commercial auto if my employees drive their own cars for work?
You may not need a full commercial auto policy, but you should look at hired and non-owned auto coverage. After a crash the employee's own policy usually pays first, yet your business can still be sued when the damages run past those limits. HNOA covers that liability, not the employee's car.
How much is commercial auto insurance in California?
It depends too much on the details for one number to be useful. A cargo van on local service calls prices very differently from three dump trucks with several drivers. Give us the vehicles, drivers, garaging ZIP codes, travel radius and the limits you want, and we'll compare carriers such as NEXT and Travelers side by side.
Am I covered if I drive the company truck on the weekend?
Usually, yes. A business auto policy generally covers the listed vehicle for any use by you and anyone driving with your permission. The gap runs the other way: if your only vehicle is on a business policy, you may have no coverage when you drive a car you don't own, like a rental. A drive other car endorsement can close that gap.
What should we do after an accident in a company vehicle?
Call 911 if anyone is hurt, exchange information, take photos, and report the claim to us and the carrier promptly. California also requires an SR-1 report to the DMV within 10 days if anyone is injured or property damage is over $1,000. A driver hurt on the job usually goes through workers' comp. Our guide to what to do after a car accident in California has the full checklist.
Do you write commercial auto outside Santa Clarita?
Yes, for businesses based anywhere in California. Our only office is in Valencia, and quotes, signatures and certificates all happen by phone, email and e-signature, so a contractor in Palmdale or Lancaster or a delivery business in Bakersfield works with us just like a Valencia business. We're licensed in California only.
Keep reading
Related coverage
Business insurance
Small business insurance in California: general liability, BOPs, workers' comp and commercial auto, quoted through carriers such as NEXT, Travelers and Mercury from Valencia.
Learn moreGeneral liability
General liability insurance for California businesses: injuries and property damage you cause, certificates and additional insureds, quoted through carriers such as NEXT and Travelers.
Learn more
Workers' compensation
Workers' compensation insurance for California employers with one or more employees, quoted with carriers such as NEXT and Travelers from our Valencia office.
Learn more
Contractor insurance
Insurance for licensed California contractors: general liability, workers' comp, work trucks and tools, set up around CSLB rules and GC contracts.
Learn more
Business insurance in Santa Clarita
Our office is in the Valencia Industrial Center, the 1,100-acre business park just east of I-5 that's home to manufacturers, distributors and service companies.
Learn more
Car insurance
California car insurance from a Valencia agency: we compare carriers like Mercury, Travelers and Bristol West and explain your options in plain English.
Learn more
Free quote · No obligation
Get a free business insurance quote
Tell us what you want to insure and Brian will compare carriers, then we'll call you back. Prefer to talk it through? Call the office.
- Mon to Fri, 9 AM to 4 PM. During business hours we usually call back within the hour.
- CA License #0D44425 · 30 years of experience