


Home insurance · Turlock, CA
Home Insurance in Turlock, CA for Older Central Homes and Newer North-Side Houses
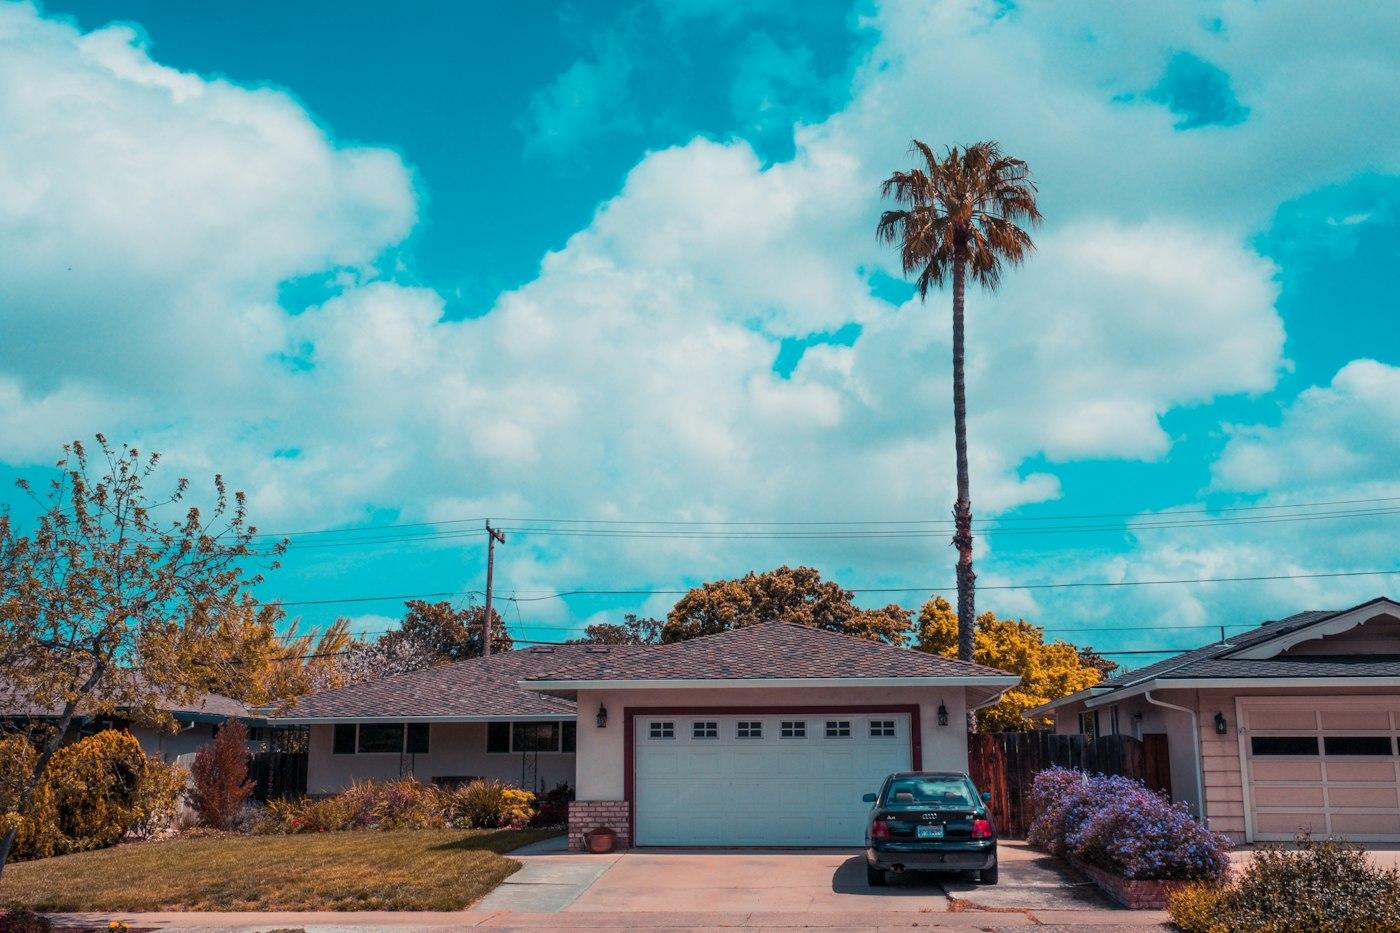
A house a few blocks east of downtown Turlock and a house off Christoffersen Parkway can sit on the same flat valley ground and still get very different home insurance quotes. The gap usually comes down to age, roof, wiring and rebuild cost. We're Brian and Dolores, an independent agency in Valencia with 30 years of experience, and Brian compares the carriers for you.
- Licensed in CA · #0D44425
- Free quotes, no obligation
- Call-back usually within the hour
Stanislaus County
Turlock, CA
Served from our Valencia office by phone, email and e-signature
More about TurlockAt a glance
- The median home citywide was built in 1984. In the census tract just east of downtown the median is 1953; between Christoffersen Parkway and Taylor Road it's 2001 to 2004 (Census estimates, 2020 to 2024).
- Standard homeowners policies in California leave out earthquake and flood damage; each takes a separate policy.
- The City of Turlock lists the city in FEMA flood Zone X, where federal rules don't require flood insurance, though a lender can.
- We can quote carriers such as Mercury Insurance and Travelers for homeowners, and Steadily and Obie for houses you rent out.
On this page8
Why do older and newer Turlock homes get different quotes?
Short answer
Carriers price a home on its rebuild cost and on how likely a claim is, and original wiring, old pipes or an aging roof push that likelihood up. A house from the early 2000s usually answers those questions more easily.
The age split shows up clearly in Census data. In the census tract just east of downtown, about half the homes date to 1953 or earlier. Between Christoffersen Parkway and Taylor Road, near Pitman High School, the median build year is 2001 to 2004. Citywide it's 1984.
What carriers ask about an older home
- Roof: the material and the year it was last replaced.
- Electrical: an upgraded panel, or original wiring still in the walls.
- Plumbing: galvanized steel, copper or PEX, and the water heater's age.
- Heating and cooling: when the furnace and air conditioner were replaced.
- Remodels: what changed and whether it was permitted.
Dates and receipts for those updates help. Some carriers turn down older homes that haven't been updated, which is one reason we quote more than one company.
What changes with a newer north-side home
Houses built around 2000 usually raise fewer questions about their systems. The focus moves to rebuild cost, since a larger two-story house with upgraded finishes costs more to replace.
Is your Turlock home insured for what it would cost to rebuild?
Short answer
It should be. The dwelling limit has to cover rebuilding from the ground up at current construction prices, which differs from the sale price because the sale price includes the land.
We estimate rebuild cost with the carrier's tools, from square footage, construction type and finishes, then set the rest of the policy around it:
- Other structures: a detached garage, fence, shed or backyard shop.
- Personal property: furniture, clothes, electronics and tools, at replacement cost if you choose that option.
- Loss of use: rent and extra living costs if a covered loss forces you out during repairs.
- Liability: injuries to guests and damage you accidentally cause to others, plus legal defense.
- Medical payments: smaller medical bills for a guest hurt at your home, regardless of fault.
Ask about extended replacement cost
Some policies add a cushion above the dwelling limit in case building prices jump after a big loss. It's worth asking about on any house.
For the statewide picture, our California home insurance page explains policy types, and the non-renewal guide covers what to do if a carrier drops you.
Does a Turlock home need flood or earthquake insurance?
Short answer
Neither is part of a standard homeowners policy, and neither is required for most homes in town. Adding them comes down to how much damage you could pay for yourself.
Flood
The city's own profile lists it in FEMA flood Zone X, which FEMA uses for moderate to minimal flood hazard. Federal rules don't require flood insurance there, though a lender can. Zones are drawn property by property, so check your address on the FEMA Flood Map Service Center (opens in a new tab).
A backed-up sewer line is a different problem from a flood. Water backup coverage is often an optional add-on to a homeowners policy, and it's worth a look if your house still has its original sewer lateral.
Earthquake
Earthquake damage is excluded from standard California homeowners policies. The California Earthquake Authority sells its policies only through participating insurance companies, and some private carriers offer their own. Our earthquake insurance page explains how the deductibles and limits work.
Can you insure a rental house near Stanislaus State?
Short answer
Yes. A house you rent out needs a landlord policy, also called a dwelling fire policy, rather than a homeowners policy. We can quote carriers such as Steadily and Obie, depending on the property and each carrier's underwriting.
Renting is common here. About four in ten occupied homes in the city are rented, according to Census estimates, and Stanislaus State adds student renters to the mix. A landlord policy usually covers:
- The building and other structures: the house, garage and fences.
- Your liability as the owner: if someone is hurt and blames the property's condition.
- Lost rent: income you lose while a covered loss is repaired, depending on the policy.
It doesn't cover your tenants' belongings. Asking tenants to carry renters insurance closes that gap, and our landlord insurance page covers the rest.
Quote your home or rental
Send the address, year built and roof age. Brian will compare carriers and call you with options.
Does living outside the city limits change the quote?
Short answer
It can. Insurers use a community fire protection rating that looks at the local fire department, water supply and emergency communications, so a home in the country near Denair or Hilmar may rate differently than one inside the city.
The rating, called the Public Protection Classification, runs from Class 1, the strongest protection, to Class 10, which means no recognized protection. For homes in the country, the distance to the nearest fire station and hydrant can affect the class, so tell us if your closest hydrant is a long way off.
Acreage brings its own questions. A barn, a big shop or animals on the property can change which policy fits, and a working farm or dairy usually needs a specialty farm policy. Tell us what's on the land and we'll be straight about what we can place.
Can I insure my home and cars together?
Short answer
Yes, with one carrier. Mercury and Travelers both write home and auto insurance, and many companies give a multi-policy discount when you insure both, depending on the carrier.
We still price the bundle against separate policies, because the combined number isn't always lower. See our home and auto bundle page and our page on car insurance in Turlock.
What do you need to quote a home here?
Short answer
The address, year built, square footage, roof type and age, details on any updates, and your current declarations page if you have one. If you're buying, your lender will want proof of coverage before closing.
- 1
Send the property details
Address, year built, size, roof, and any updates to wiring, plumbing or heating.
- 2
We set the rebuild cost
So the dwelling limit fits the house, not the sale price.
- 3
We compare carriers
Including Mercury and Travelers for homes you live in, and Steadily and Obie for rentals.
- 4
Sign and send proof
You sign by e-signature, and we can email the declarations page to your lender or escrow.
It all happens by phone, email and e-signature from Valencia. Family elsewhere can get home insurance in Modesto, Bakersfield or Santa Clarita, and our Turlock insurance overview covers renters and business policies.
Sources we used for this page (7)
- 1Census Reporter: Median year structure built, Turlock and its census tracts (ACS 2020 to 2024, table B25035) (opens in a new tab)censusreporter.org
- 2Census Reporter: Turlock, CA (housing and tenure, ACS 2020 to 2024) (opens in a new tab)censusreporter.org
- 3City of Turlock: About Turlock (flood zone) (opens in a new tab)turlock.ca.us
- 4FEMA: Flood zones glossary (opens in a new tab)fema.gov
- 5FEMA Flood Map Service Center (opens in a new tab)msc.fema.gov
- 6Verisk: Public Protection Classification (PPC) FAQ (opens in a new tab)verisk.com
- 7California Earthquake Authority (opens in a new tab)earthquakeauthority.com
Turlock
Also in Turlock
Other areas we serve
Home insurance in other cities
Questions we hear a lot
Home insurance in Turlock: common questions
Short answers to what people ask us most. Anything else, call and ask Brian or Dolores.
Still have a question?
Talk to a licensed agent at the Valencia office.
(818) 909-7486Mon to Fri, 9 AM to 4 PM
How much is home insurance in Turlock?
It depends on the house. Carriers look at the rebuild cost, the age and construction, the roof, your claims history, the deductible you pick and the local fire protection rating, so two homes on the same street can price differently. We don't post averages that won't match your house. A free quote with your address and year built gives you real figures from more than one carrier.
Is my Turlock home in a flood zone?
Probably not a high-risk one, but check your address. The city's profile puts it in FEMA flood Zone X, a moderate-to-minimal hazard category where flood insurance isn't federally required. FEMA maps zones parcel by parcel, so look up your property on its Flood Map Service Center. Standard homeowners policies exclude flood no matter which zone you're in.
Does an older house near downtown Turlock cost more to insure?
It can, though updates matter more than the year it was built. A 1950s house with a newer roof, an upgraded electrical panel and replaced plumbing may quote close to a much newer home. Original systems raise more questions, and some carriers won't take them at all. Keep receipts for updates, because they help us place the house with more companies.
I just bought a new house in north Turlock. What should I check?
Check that the dwelling limit reflects rebuild cost, not the purchase price, and that the personal property and liability limits fit your household. Ask about water backup and extended replacement cost. A builder's warranty covers construction defects, not fire, theft or liability, so it doesn't replace a homeowners policy. Your lender will also need proof of insurance before closing.
Do I need earthquake insurance in the Central Valley?
It isn't required, so it's your call. Standard California homeowners policies exclude earthquake damage, which means quake repairs would come out of your pocket without a separate policy. The California Earthquake Authority offers policies through participating insurers, and some private carriers write their own. Compare the deductible, usually a percentage of the dwelling limit, with what you could afford to cover.
Do I need a different policy for a home on acreage outside town?
Sometimes. A house on a few acres can often go on a homeowners policy, but barns, large shops, livestock or a farm operation can push it toward a different kind of policy. Distance to a fire station and hydrant also matters. Tell us what's on the property, and we'll tell you plainly whether we can place it.
Keep reading
Related coverage
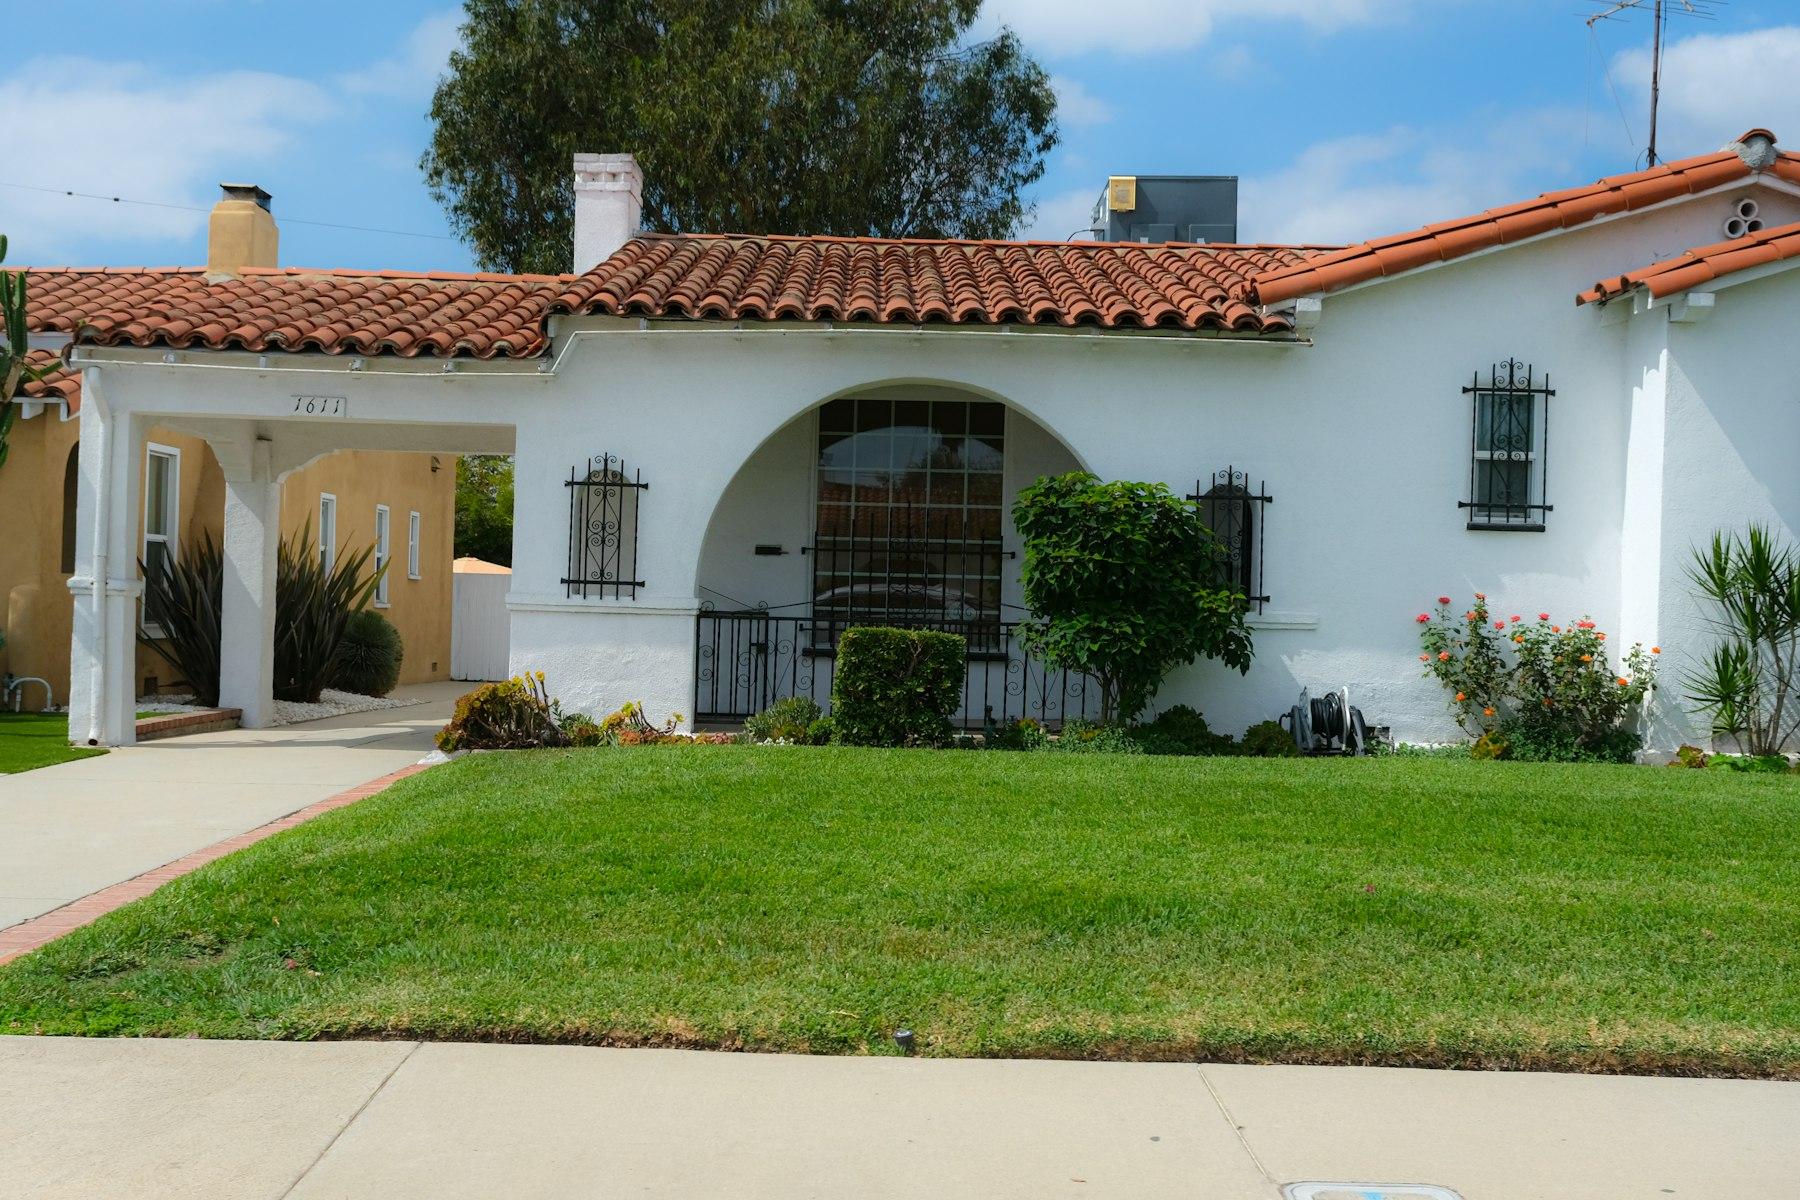
Home insurance
Homeowners insurance for California houses, quoted with carriers like Mercury and Travelers by a family-run independent agency in Valencia.
Learn more
Landlord insurance
Landlord and dwelling fire insurance for California rental homes, condos and small multi-unit buildings, quoted with carriers such as Steadily, Obie and Mercury.
Learn more
Earthquake insurance
Separate earthquake coverage for California homes, condos and renters, with help comparing CEA and private policy options.
Learn more
Home & auto bundle
Home and two-car auto policies priced together and separately, so you can see whether bundling with one carrier pays off.
Learn moreGot a home insurance non-renewal?
A non-renewal letter means your insurer won't offer you another term when this policy ends.
Learn more
Free quote · No obligation
Get a free home insurance quote in Turlock
Tell us what you want to insure and Brian will compare carriers, then we'll call you back. Everything happens by phone, email and e-signature, so there's no need to drive to Valencia.
- Mon to Fri, 9 AM to 4 PM. During business hours we usually call back within the hour.
- CA License #0D44425 · 30 years of experience