


Home insurance · Orange County, CA
Home Insurance in Orange County, CA, From the Coast to the Canyons
A townhome in Irvine, a hillside house in Anaheim Hills and a cottage near the sand in Newport Beach sit in the same county but call for three different insurance setups. We're an independent agency in Valencia with 30 years of experience. We quote Orange County homeowners with carriers such as Mercury and Travelers and point out the gaps (wildfire, flood, earthquake) before you sign anything.
- Licensed in CA · #0D44425
- Free quotes, no obligation
- Call-back usually within the hour
Orange County
Orange County, CA
Served from our Valencia office by phone, email and e-signature
More about Orange CountyAt a glance
- Homeowners and condo policies don't cover flood or earthquake, and FEMA says a new NFIP flood policy typically has a 30-day waiting period.
- Your HOA has to summarize its insurance in the annual budget report (California Civil Code section 5300). That summary shows what your HO-6 policy needs to pick up.
- Per CAL FIRE, the 2024 Airport Fire destroyed 160 structures as it burned from Trabuco Canyon into Riverside County.
- Insurers judge wildfire with their own risk models, not CAL FIRE's hazard maps, and California's Safer from Wildfires rules require discounts for qualifying fire-hardening work.
- We can quote carriers such as Mercury Insurance and Travelers for homes and Steadily or Obie for rentals, all by phone and e-sign from Valencia.
On this page7
What does an HO-6 policy need to cover in an Orange County HOA?
Short answer
Whatever the HOA's master policy leaves to you: usually the inside of your unit, your belongings, your liability and your share of any special assessment. Your CC&Rs and the HOA's insurance summary show where that line falls.
California Civil Code section 5300 requires the association's annual budget report to summarize its property, general liability, earthquake, flood and fidelity insurance, and to remind owners to check with their own agent about additional coverage. Under Civil Code section 4775, unless the CC&Rs say otherwise, the association repairs the common areas and each owner repairs their own unit. Send us both documents and we'll build your condo (HO-6) policy around them.
- Walls-in coverage: the parts of the unit the master policy skips, which can include interior walls, flooring, cabinets and fixtures.
- Loss assessment: your share when the HOA bills owners after a covered loss to common property. Whether it also helps with an assessment for the master deductible depends on the policy.
- Your things, your liability and loss of use: belongings, injuries to guests inside your unit, and hotel or rent money while covered repairs are made.
Detached house in an HOA?
Some planned communities charge HOA dues on detached houses too. If you own the whole house, you usually need a regular homeowners policy (HO-3), not an HO-6, because the HOA typically insures only the common areas.
How does wildfire risk change home insurance in the canyons and foothills?
Short answer
It narrows your choices. Each carrier judges wildfire with its own model, so a home next to brush can be declined by one company, accepted by another, or end up on the California FAIR Plan.
The 2017 Canyon Fire 2 burned into Anaheim Hills. In October 2020 the Silverado Fire burned 12,466 acres off the 241 near Irvine, and that December the Bond Fire began as a house fire in Silverado Canyon and spread into the hills. Wildfire isn't only an inland issue, either: in May 2022 the Coastal Fire destroyed at least 20 homes on a hillside in Laguna Niguel, close to the coast.
The California Department of Insurance has said CAL FIRE's Fire Hazard Severity Zone maps aren't used for insurance rates or underwriting. Your own work counts more: the Safer from Wildfires regulation requires insurers to discount qualifying steps and to share your wildfire risk score, with a way to appeal it. Those steps include:
- A Class A fire-rated roof
- A five-foot ember-resistant zone cleared around the house
- Upgraded windows, plus defensible space beyond that zone
- A neighborhood recognized under Firewise USA
After a declared wildfire
After a declared wildfire emergency, Insurance Code section 675.1 bars insurers from non-renewing homes in and around the fire area for one year simply because a wildfire occurred there. The Insurance Commissioner applied that moratorium to ZIP codes in Orange and Riverside counties after the 2024 Airport Fire. If a non-renewal arrives after that year, start with our non-renewal guide.
If no standard carrier will write the home, the California FAIR Plan offers a basic fire policy, and owners often add a difference-in-conditions (DIC) policy from another insurer for liability, theft and water damage.
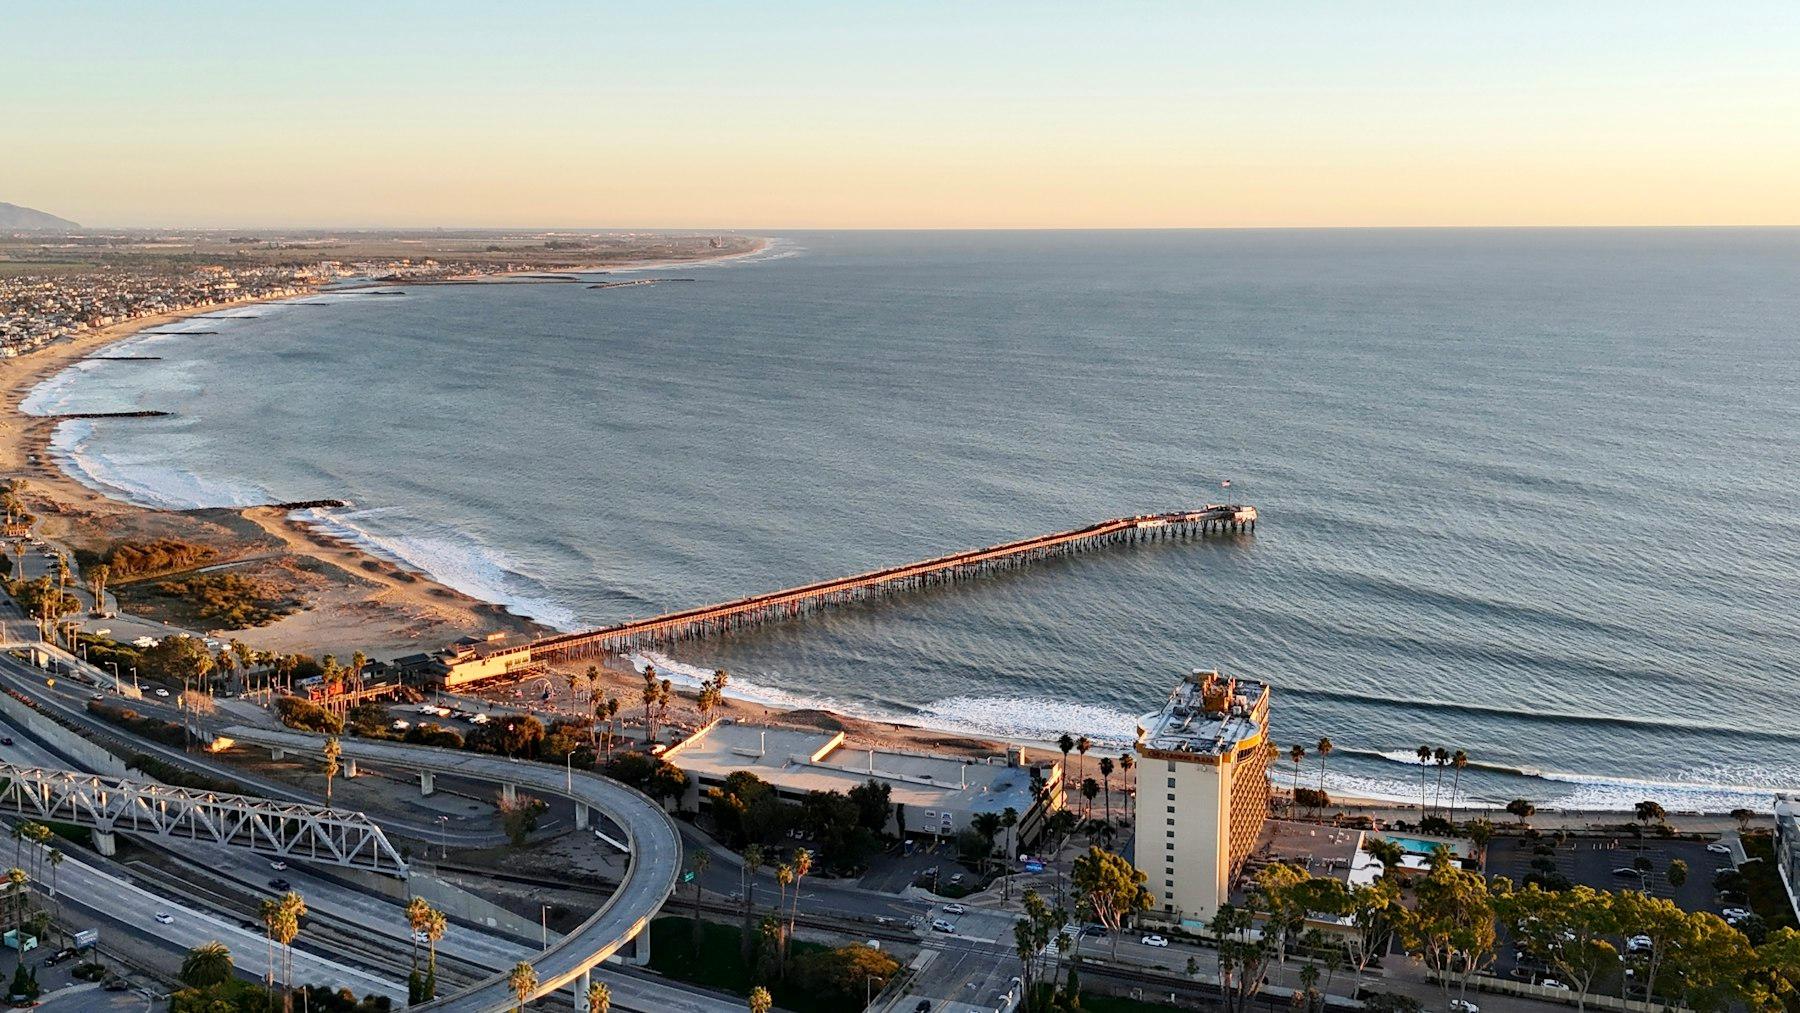
Do homes near the coast need flood insurance?
Short answer
Your lender will require it if the home is in a FEMA high-risk flood zone and the mortgage is federally backed. Elsewhere it's usually optional, but homeowners policies generally exclude flood, so it's worth pricing for low-lying homes near the beaches and harbors.
The City of Newport Beach notes that federal law requires flood insurance on federally backed loans in designated flood hazard zones, and that lenders use FEMA's maps to decide. You can look up any address on FEMA's Flood Map Service Center (opens in a new tab).
Flood policies come from the National Flood Insurance Program (NFIP) or private insurers. Buy well before the rainy season, since an NFIP policy usually takes 30 days to start.
Is earthquake insurance worth it for a home in Orange County?
Short answer
That depends on your savings and your mortgage, but no standard homeowners or condo policy pays for earthquake damage. The Newport-Inglewood fault, source of the magnitude 6.4 Long Beach earthquake of 1933, runs along the county's coast.
The Southern California Earthquake Data Center traces the fault near Seal Beach, Huntington Beach, Costa Mesa and Newport Beach before it heads offshore south of Newport Bay. The California Geological Survey's EQ Zapp map shows whether an address sits in a mapped liquefaction or landslide zone.
Coverage comes from the California Earthquake Authority (opens in a new tab) or a private insurer. CEA deductibles are a percentage of the coverage limit, not a flat amount, so pick one you could pay. A CEA condo policy also offers up to $100,000 of loss assessment coverage for your share of certain HOA assessments after an earthquake, such as repairs to the building exterior or common areas. Our earthquake insurance page compares the options.
How much dwelling coverage does your home need?
Short answer
Enough to rebuild the house at current construction costs. That's a different number from the market value, because much of a home's price in Orange County can be the land, and land doesn't need rebuilding.
Carriers estimate rebuilding cost from square footage, construction type, roof, interior finishes and the year built. Two features earn their keep after a big fire: extended replacement cost, which adds a cushion above the dwelling limit if building costs spike, and building code upgrade coverage, since a rebuilt home has to meet current code. Recheck the limit after any remodel.
Which companies can you quote for Orange County homes and condos?
Short answer
The companies we can quote include Mercury Insurance and Travelers for homeowners policies, Mercury for condos, and Steadily and Obie when the property is a rental. Whether a carrier will write a particular home is up to its underwriting.
Home policies we can quote
House you live in
- Policy type
- Homeowners (HO-3)
- Carriers we can quote include
- Mercury Insurance, Travelers
Condo or townhome in an HOA
- Policy type
- Condo unit-owner (HO-6)
- Carriers we can quote include
- Mercury Insurance
House or condo you rent out
- Policy type
- Landlord (dwelling) policy
- Carriers we can quote include
- Steadily, Obie (see landlord insurance)
| Property | Policy type | Carriers we can quote include |
|---|---|---|
| House you live in | Homeowners (HO-3) | Mercury Insurance, Travelers |
| Condo or townhome in an HOA | Condo unit-owner (HO-6) | Mercury Insurance |
| House or condo you rent out | Landlord (dwelling) policy | Steadily, Obie (see landlord insurance) |
Get a home quote
Have your address, year built, roof type and current declarations page ready. We handle the rest by phone, email and e-signature, with no office visit.
Two cars as well? Ask about pairing this with auto insurance in Orange County in a home and auto bundle. For the statewide view, see homeowners insurance in California; for everything we cover locally, our Orange County insurance page. We also quote home insurance in Santa Clarita, Ventura and Bakersfield.
Sources we used for this page (14)
- 1CAL FIRE: Silverado Fire (2020) (opens in a new tab)fire.ca.gov
- 2CAL FIRE: Airport Fire (2024) (opens in a new tab)fire.ca.gov
- 310News: Bond Fire started by a house fire in Silverado Canyon (opens in a new tab)10news.com
- 4ABC7: Coastal Fire destroys 20 homes in Laguna Niguel (opens in a new tab)abc7.com
- 5California Department of Insurance: CAL FIRE hazard maps do not affect insurance rates or availability (opens in a new tab)insurance.ca.gov
- 6California Department of Insurance: Safer from Wildfires regulation (opens in a new tab)insurance.ca.gov
- 7California Department of Insurance: Moratorium after the Airport, Bridge and Line fires (opens in a new tab)insurance.ca.gov
- 8FEMA: Flood insurance (opens in a new tab)fema.gov
- 9City of Newport Beach: Flood map FAQs (opens in a new tab)newportbeachca.gov
- 10Southern California Earthquake Data Center: Newport-Inglewood Fault Zone (opens in a new tab)scedc.caltech.edu
- 11California Geological Survey: EQ Zapp (opens in a new tab)conservation.ca.gov
- 12California Earthquake Authority: Condo coverages and deductibles (opens in a new tab)earthquakeauthority.com
- 13California Civil Code section 5300 (opens in a new tab)leginfo.legislature.ca.gov
- 14California Civil Code section 4775 (opens in a new tab)leginfo.legislature.ca.gov
Orange County
Also in Orange County
Other areas we serve
Home insurance in other cities
Questions we hear a lot
Home insurance in Orange County: common questions
Short answers to what people ask us most. Anything else, call and ask Brian or Dolores.
Still have a question?
Talk to a licensed agent at the Valencia office.
(818) 909-7486Mon to Fri, 9 AM to 4 PM
How much does home insurance cost in Orange County?
There's no honest county-wide number. Premiums depend on the cost to rebuild the house, its roof and age, the wildfire exposure at that exact address, your claims history and your deductible. Two homes on one street can price differently if one has a newer roof or more brush nearby. We'll quote your actual home and show how the deductible changes the price.
What should I do if my home insurance is non-renewed?
Start shopping as soon as the notice arrives, and call us. We'll check whether Mercury, Travelers or another carrier we work with can offer a policy and, if none can, explain the FAIR Plan with a difference-in-conditions policy. Document any fire-hardening upgrades, since Safer from Wildfires rules let you see and appeal your wildfire risk score. The Department of Insurance hotline, 800-927-4357, also takes questions.
Does an HOA master policy cover the inside of my condo?
Sometimes, partly. Some master policies cover only the bare structure; others also cover original fixtures and finishes inside the units. The insurance summary in your HOA's annual budget report and your CC&Rs tell you which kind you have. Your HO-6 fills in the rest, and it's worth comparing your loss assessment limit with the master policy's deductible.
Can I get homeowners insurance in Silverado Canyon or Trabuco Canyon?
Possibly, but expect fewer choices and more questions. Carriers look closely at the roof, the nearby brush, how the house is built and its distance from a fire station. We start with the carriers we work with; if none can offer a policy, the FAIR Plan exists for this situation, usually alongside a DIC policy. Hardening the home can help with both eligibility and discounts.
Is flood insurance required in Huntington Beach or Newport Beach?
Only for some homes: those in a FEMA Special Flood Hazard Area with a federally backed mortgage. Outside those zones federal law doesn't require it, though a homeowners policy still won't pay for flood damage. Check the address on FEMA's flood map before you buy, and allow for the usual 30-day wait on a new NFIP policy.
Do you insure rental homes and condos in the county?
Yes. A house or condo you rent out needs a landlord (dwelling) policy, not a homeowners policy, and we can quote carriers such as Steadily and Obie for it. It protects the structure and your liability as the owner, and many can add fair rental value (lost rent) after a covered loss. Your tenants' belongings need their own renters policy.
Keep reading
Related coverage
Home insurance
Homeowners insurance for California houses, quoted with carriers like Mercury and Travelers by a family-run independent agency in Valencia.
Learn more
Condo insurance
HO-6 condo insurance for California owners: walls-in coverage, loss assessment and liability, quoted with carriers such as Mercury and Travelers from Valencia.
Learn more
Earthquake insurance
Separate earthquake coverage for California homes, condos and renters, with help comparing CEA and private policy options.
Learn moreCalifornia FAIR Plan guide
The California FAIR Plan is where a house goes when regular insurers say no.
Learn more
Landlord insurance
Landlord and dwelling fire insurance for California rental homes, condos and small multi-unit buildings, quoted with carriers such as Steadily, Obie and Mercury.
Learn more
Free quote · No obligation
Get a free home insurance quote in Orange County
Tell us what you want to insure and Brian will compare carriers, then we'll call you back. Everything happens by phone, email and e-signature, so there's no need to drive to Valencia.
- Mon to Fri, 9 AM to 4 PM. During business hours we usually call back within the hour.
- CA License #0D44425 · 30 years of experience