


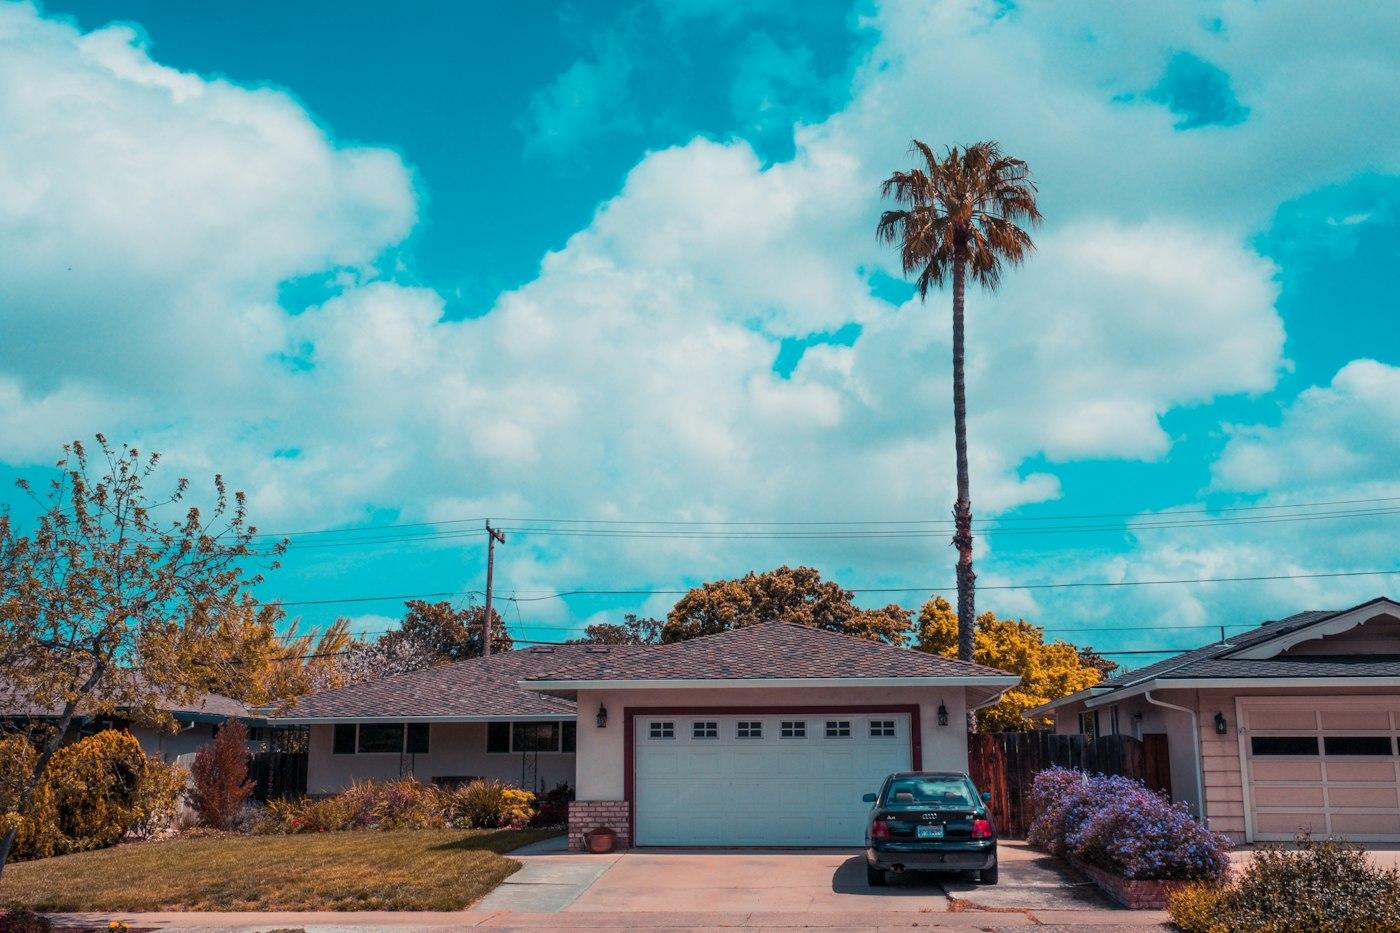
Home insurance · Bakersfield, CA
Homeowners Insurance in Bakersfield, CA, From Westchester to Seven Oaks
A 1940s house in Westchester and a 2000s house in Seven Oaks may hear two different things from the same insurer, and Bakersfield summers test every roof and air conditioner in town. We're a family-run independent agency based in Valencia, with 30 years of experience. We compare homeowners quotes and handle the whole policy by phone, email and e-signature.
- Licensed in CA · #0D44425
- Free quotes, no obligation
- Call-back usually within the hour
Kern County
Bakersfield, CA
Served from our Valencia office by phone, email and e-signature
More about BakersfieldAt a glance
- A standard California homeowners policy doesn't cover earthquake or flood damage. Each needs its own policy.
- In August 1952, a magnitude 5.8 aftershock of the Kern County earthquake damaged brick buildings across a 64-block area of downtown Bakersfield.
- Insurers ask about roof age and updates to wiring, plumbing and heating and cooling, especially in older central neighborhoods.
- We can quote carriers such as Mercury and Travelers for homes and Steadily and Obie for rentals, all by phone, email and e-signature.
On this page7
What does homeowners insurance cover in Bakersfield?
Short answer
A standard HO-3 policy covers the house, other structures like fences and detached garages, your belongings, your liability if someone is hurt, and extra living costs while covered damage keeps you out of the house. It doesn't cover earthquake, flood or wear and tear.
- Dwelling: repairs or rebuilds the house after fire, wind, hail, a burst pipe or another covered event.
- Other structures: block walls, fences, sheds and detached garages.
- Personal property: furniture, clothing and electronics, including things stolen from your car.
- Liability and medical payments: a guest's fall by the pool, or damage you accidentally cause to someone else.
- Loss of use: hotel, rent and meal costs while covered damage is repaired.
Wind and hail are rare here, but not unheard of. Weather Service records describe downslope winds that can reach 50 mph, a December 1977 dust storm with gusts over 60 mph that damaged buildings and trees, and hail an inch and a half across on the southwest side in February 1997. Wind and hail damage is normally covered, minus your deductible.
How does the age of your house affect the quote?
Short answer
Underwriters price the condition of the roof, wiring, plumbing and heating and cooling, not just the size of the house. Updated systems usually mean more carrier options, whatever the neighborhood.
The city grew in stages. Westchester and the blocks near downtown hold some of the oldest houses, many from the first half of the 1900s. Most growth from the 1960s through the 1980s happened in the southwest, around Stockdale, Laurelglen and Haggin Oaks. Seven Oaks was built out from the 1990s on, and the northwest around Rosedale and Riverlakes Ranch grew mostly after the mid-1990s.
What underwriters tend to ask, by type of house
Built before 1960
- Where you often find it
- Westchester and around downtown
- Questions to expect
- Wiring and panel updates, original plumbing, roof age
1960s to 1980s ranch house
- Where you often find it
- Stockdale, Laurelglen and the rest of the southwest
- Questions to expect
- Roof date, AC and furnace age, panel upgrades
1990s and newer
- Where you often find it
- Seven Oaks, Rosedale, Riverlakes Ranch
- Questions to expect
- Rebuilding cost, pools, solar panels
Foothill or canyon home
- Where you often find it
- East toward the Kern River Canyon
- Questions to expect
- Wildfire score, brush clearance, roof material
| Type of house | Where you often find it | Questions to expect |
|---|---|---|
| Built before 1960 | Westchester and around downtown | Wiring and panel updates, original plumbing, roof age |
| 1960s to 1980s ranch house | Stockdale, Laurelglen and the rest of the southwest | Roof date, AC and furnace age, panel upgrades |
| 1990s and newer | Seven Oaks, Rosedale, Riverlakes Ranch | Rebuilding cost, pools, solar panels |
| Foothill or canyon home | East toward the Kern River Canyon | Wildfire score, brush clearance, roof material |
Have the roof year and any updates ready when you call. Permits or receipts for a new panel, re-piping or a new AC unit can bring in carriers that would otherwise pass.
Does home insurance cover a broken AC in July?
Short answer
Usually not. An air conditioner that wears out is a maintenance issue, which is what a home warranty or service plan is for. Insurance pays when a covered event, like a fire or a lightning strike, damages the unit, or when a sudden leak damages the house.
Normal July highs here sit in the mid to upper 90s, some summers reach 110, and air conditioners run hard from June into September. Water is the bigger insurance question. A slow condensate leak that rots drywall over months is usually excluded as gradual damage, while a sudden burst that soaks a ceiling is usually covered. Water heaters and supply lines follow the same rule.
Sun and heat also age roofs, and many carriers ask for the exact year yours was replaced. A home warranty and homeowners insurance do different jobs, and your mortgage lender requires only the insurance.
Is wildfire a concern for Bakersfield homeowners?
Short answer
It depends on where the house sits. Most of the city is on the flat valley floor, but the Sierra Nevada foothills start about 10 miles east, and homes toward the Kern River Canyon and the mountains can face more wildfire exposure and tougher underwriting.
Fires in the Kern River Canyon have closed Highway 178 more than once, and fires around Lake Isabella have destroyed homes. Kern County Fire has pointed out that CAL FIRE's fire hazard severity zones are hazard maps, not insurance risk maps. Insurers run their own wildfire scores, so two carriers can see the same address differently.
If a carrier non-renews you or won't quote, you still have options. Our California non-renewal guide explains what to do next, while the FAIR Plan guide explains the state's fallback policy and the DIC policy people often add to it.
Do Bakersfield homes need earthquake insurance?
Short answer
It's worth pricing. The area has a real earthquake history, and a standard homeowners policy excludes earthquake damage, so shaking coverage has to come from a separate policy.
On July 21, 1952, the Kern County earthquake ruptured the White Wolf fault south of the city and killed 12 people. A month later, on August 22, a magnitude 5.8 aftershock centered about six miles east-southeast of Bakersfield did most of its damage to brick buildings across a 64-block area downtown. That history is why we bring up earthquake coverage with every homeowner we quote here.
The California Earthquake Authority sells policies through participating home insurers, and private options exist too. Our earthquake insurance page explains the choices, and the CEA website (opens in a new tab) has a premium estimate tool.
Get a homeowners quote
Send your address, roof year and current declarations page, and we'll compare homeowners options and talk through earthquake coverage.
Can we quote your home without visiting it?
Short answer
Yes. Your address, year built, roof year, updates and current declarations page are enough to compare carriers, and you sign by e-signature when you're ready.
- 1
Tell us about the house
Address, year built, square footage, roof year, and what has been updated: wiring, plumbing, heating or cooling.
- 2
We shop it
We check carriers such as Mercury and Travelers and explain how each one would treat your house.
- 3
Sign and finish
Choose a policy, e-sign it on your phone, and we can send proof of insurance to your mortgage lender.
Own a rental too? We can quote a landlord policy through carriers like Steadily or Obie, and condo owners need an HO-6 condo policy. To pair the house with your cars, see car insurance in Bakersfield and the home and auto bundle.
We also quote homeowners insurance in Santa Clarita, Modesto and Palmdale. For the statewide picture, read about homeowners insurance in California. Everything else we quote in Kern County is on our Bakersfield insurance page.
Sources we used for this page (4)
- 1Southern California Earthquake Data Center (Caltech): 1952 Kern County earthquake (opens in a new tab)scedc.caltech.edu
- 2NOAA Technical Memorandum NWS WR-281: The Climate of Bakersfield, California (opens in a new tab)weather.gov
- 3California Earthquake Authority (opens in a new tab)earthquakeauthority.com
- 4FEMA Flood Map Service Center (opens in a new tab)msc.fema.gov
Bakersfield
Also in Bakersfield
Other areas we serve
Home insurance in other cities
Questions we hear a lot
Home insurance in Bakersfield: common questions
Short answers to what people ask us most. Anything else, call and ask Brian or Dolores.
Still have a question?
Talk to a licensed agent at the Valencia office.
(818) 909-7486Mon to Fri, 9 AM to 4 PM
How much is homeowners insurance in Bakersfield?
It depends on the house and the address. Rebuilding cost, roof age, the condition of the major systems, your claims history, your deductible and each carrier's wildfire score all play a part. A published average would rarely match your quote, so we'd rather compare actual numbers for you at no cost.
Can I insure an older house in Westchester or near downtown?
Usually, especially if the roof, wiring and plumbing have been updated. Original fuse boxes, some older electrical panels and galvanized pipes can limit which carriers will quote, so permits or receipts for updates help. If no standard carrier will take the house, the California FAIR Plan is the fallback for fire coverage, often paired with a separate DIC policy.
Does a homeowners policy cover earthquake damage?
No. California homeowners policies exclude earthquake damage, so you need a separate earthquake policy, either from the California Earthquake Authority through a participating insurer or from a private carrier. Given the 1952 Kern County earthquake and the aftershock that hit downtown that August, we think every homeowner here should at least see the price.
Is my home near the Kern River covered for flooding?
Not by a standard homeowners policy, which excludes flood. Most of the Kern's water is diverted for farms and city use, so the riverbed through town is often dry, but the river once flooded the area that is now downtown. Check your address on FEMA's flood map (opens in a new tab) and ask us about separate flood coverage if you're in or near a mapped zone.
I rent out a house in Bakersfield. Does my homeowners policy still work?
Usually not once tenants move in. A rental needs a landlord or dwelling policy, which protects the structure, your liability as owner and, on many policies, rent you lose after a covered loss. We can quote carriers such as Steadily and Obie, two that specialize in rentals. Your tenants should carry their own renters insurance for their belongings.
Will someone need to inspect my house?
Not from our office. We work by phone, email and e-signature from Valencia, so we never need to see the house to quote it. Some carriers do order their own inspection after a policy is issued. If yours does, we'll tell you what to expect and help sort out anything the inspector flags.
Keep reading
Related coverage
Home insurance
Homeowners insurance for California houses, quoted with carriers like Mercury and Travelers by a family-run independent agency in Valencia.
Learn more
Earthquake insurance
Separate earthquake coverage for California homes, condos and renters, with help comparing CEA and private policy options.
Learn more
Home & auto bundle
Home and two-car auto policies priced together and separately, so you can see whether bundling with one carrier pays off.
Learn more
Landlord insurance
Landlord and dwelling fire insurance for California rental homes, condos and small multi-unit buildings, quoted with carriers such as Steadily, Obie and Mercury.
Learn more
California FAIR Plan guide
The California FAIR Plan is where a house goes when regular insurers say no.
Learn more
Free quote · No obligation
Get a free home insurance quote in Bakersfield
Tell us what you want to insure and Brian will compare carriers, then we'll call you back. Everything happens by phone, email and e-signature, so there's no need to drive to Valencia.
- Mon to Fri, 9 AM to 4 PM. During business hours we usually call back within the hour.
- CA License #0D44425 · 30 years of experience