


Home insurance · Ventura, CA
Home Insurance in Ventura, CA, and the Lessons of the Thomas Fire
When the Thomas Fire swept into the hillsides in December 2017, hundreds of local families found out what their policies really said. Those who rebuilt ran into hillside pilings, newer safety rules, debris bills and long stretches of rent. We quote Ventura homes with those lessons in mind, comparing carriers from our Valencia office by phone and email.
- Licensed in CA · #0D44425
- Free quotes, no obligation
- Call-back usually within the hour
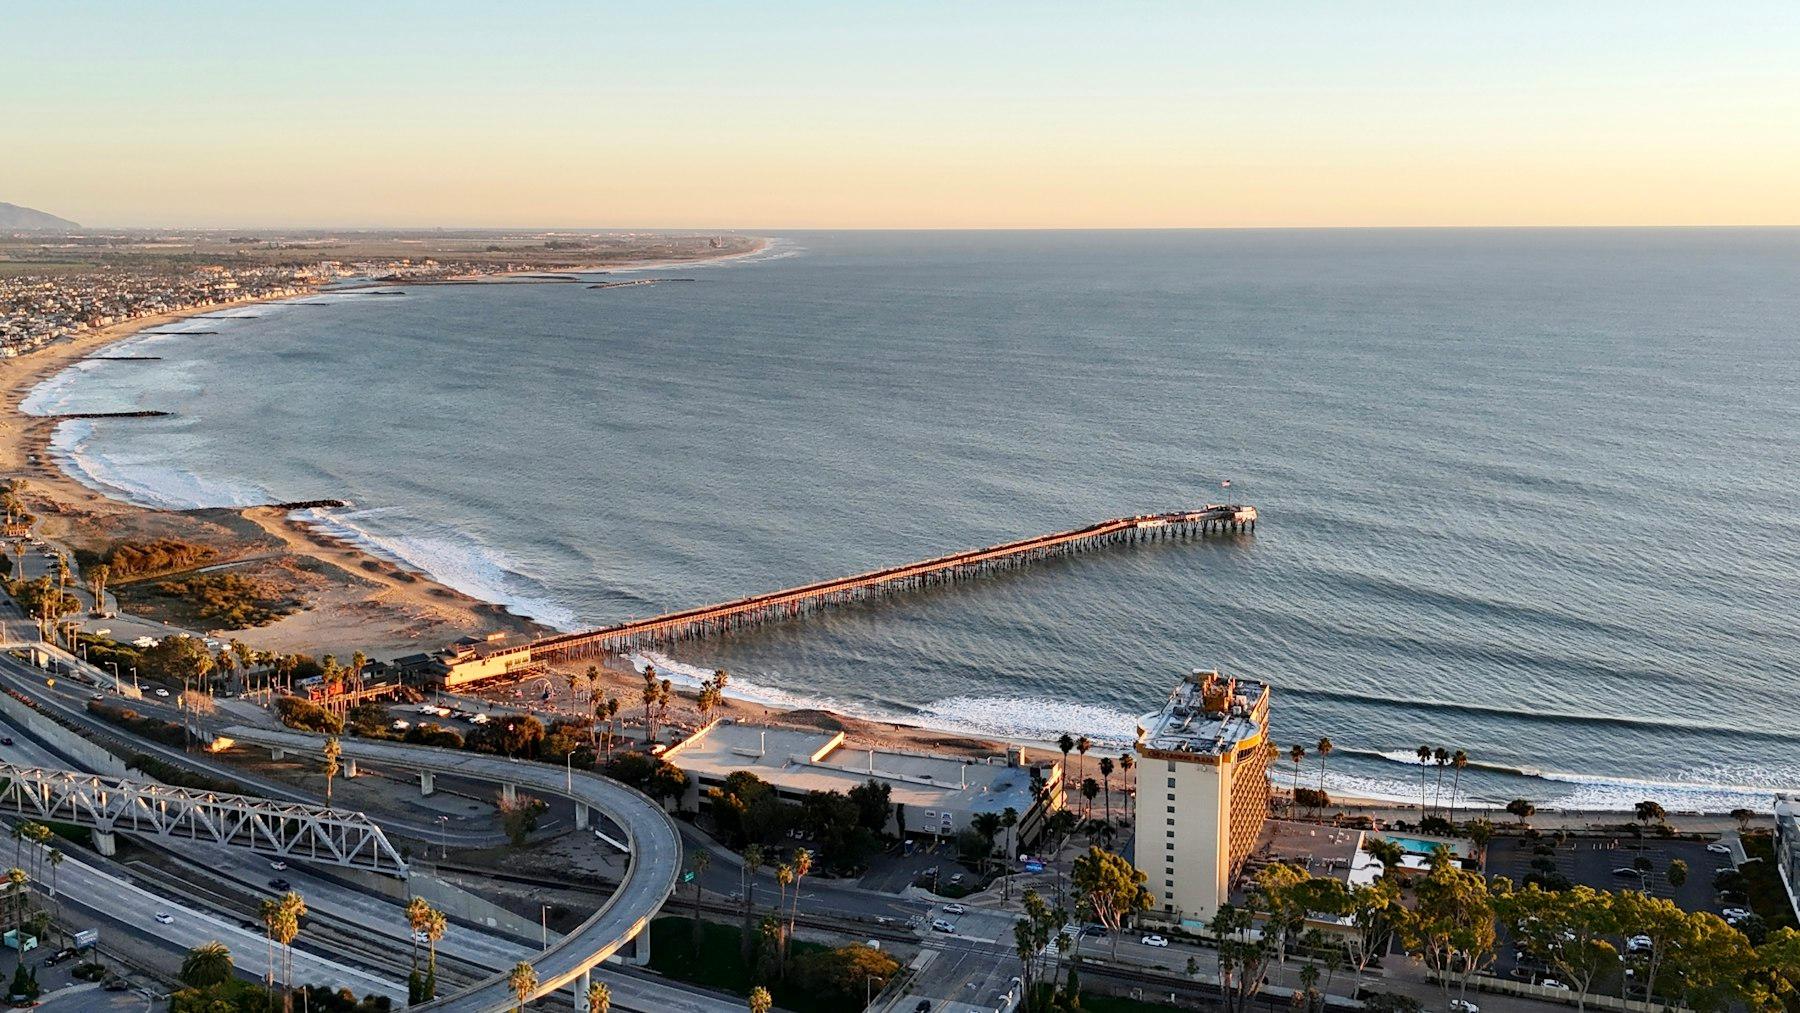
Ventura County
Ventura, CA
Served from our Valencia office by phone, email and e-signature
More about VenturaAt a glance
- CAL FIRE counts 1,063 structures destroyed by the 2017 Thomas Fire, including hundreds of homes in Ondulando, Clearpoint, Skyline and other hillside neighborhoods.
- Extended replacement cost pays above your dwelling limit, up to a set percentage or dollar amount, when rebuilding costs more than the limit.
- Replacement cost policies issued or renewed since July 1, 2021 must include building code upgrade coverage of at least 10% of the dwelling limit, on top of that limit.
- After a declared disaster, California gives you at least 36 months to collect full replacement cost and 24 months of living expenses, with extensions for delays.
On this page8
What did the Thomas Fire teach Ventura homeowners about insurance?
Short answer
That the dwelling limit is only one line of the policy. Rebuilding a hillside home brought costs a basic estimate can miss: deep foundations, current code requirements, debris hauling and a long stretch of rent.
It began north of Santa Paula on December 4, 2017. Pushed by Santa Ana winds, it reached the city's hillside neighborhoods that night, and Ondulando alone lost more than 150 homes. By containment in January 2018, it had burned 281,893 acres.
Eight years later, the Ventura County Star reported that most single-family homes lost inside city limits had been rebuilt, though many owners hit obstacles: old septic systems, steep lots needing large pilings that can cost tens of thousands of dollars apiece, and setback and safety rules that didn't exist when the original houses went up.
Each of those costs maps to a line in a homeowners policy. Here they are, one at a time.
What is extended replacement cost, and how much do you need?
Short answer
It is coverage above your dwelling limit, up to a stated percentage or dollar amount, for when rebuilding costs more than the limit. How much you need depends on how current your rebuild estimate is and how hard your lot would be to build on.
California's required disclosure form (Insurance Code section 10102) describes the levels of dwelling coverage:
- Actual cash value pays to repair or replace minus depreciation, which leaves an older house short.
- Replacement cost pays without the depreciation deduction, up to your dwelling limit. Many policies pay actual cash value first and the rest once you rebuild.
- Extended replacement cost adds a cushion above the limit, set as a percentage or a dollar amount.
The cushion only helps if the base limit is realistic, and the same form encourages getting a current rebuild estimate. Remodeled the kitchen or added a room? Tell us, so the limit grows with the house. Options and percentages vary by carrier; when we compare carriers such as Mercury Insurance and Travelers, we show what each quote includes.
How does building code upgrade coverage work in a rebuild?
Short answer
It pays the added cost of meeting the codes and zoning rules in force when you rebuild, not those in place when the house went up. Replacement cost policies issued or renewed since July 1, 2021 must include at least 10% of the dwelling limit for it, on top of the limit.
On a hillside lot, today's rules can mean stronger foundations, setbacks from the slope and fire-resistant construction. The Ventura Fire Department's updated hazard maps, released for public review in 2025, put most of the land rated for wildfire hazard in those same hillsides.
The 10% is a floor, not a recommendation, so ask whether a carrier offers more. A policy without this coverage must say so on the declarations page: "THIS POLICY DOES NOT INCLUDE BUILDING CODE UPGRADE COVERAGE." Look for that line on yours.
Who pays to clear the lot after a fire?
Short answer
Usually the debris removal coverage in your homeowners policy. Depending on the policy, that money either comes out of your dwelling limit or is paid as extra coverage on top of it, and the difference matters after a total loss.
After the Thomas Fire, the state ran a cleanup program with the county and the city; CalRecycle crews hauled 263,925 tons of debris from 672 Ventura County properties by June 2018. The county also helped survivors work out which part of their insurance was set aside for debris removal, and owners who opted out hired and paid their own contractors.
If debris removal comes out of the dwelling limit, every dollar spent hauling ash and broken concrete is a dollar not spent on framing. Ask how your policy handles it.
Check your rebuild coverage
Send us your current declarations page. We will walk through your dwelling limit, extended replacement cost and code upgrade lines, then compare quotes.
How long will insurance pay your rent while you rebuild?
Short answer
For a loss tied to a declared state of emergency, California requires at least 24 months of additional living expense coverage, plus up to 12 more months if permits, materials or contractor shortages hold you up. Your policy still sets the dollar limit.
Additional living expense (ALE, or loss of use) covers the extra cost of living elsewhere: rent, mileage, storage. Two years of coastal rent adds up, so check the ALE dollar limit as closely as the time limit.
California minimums after a declared disaster (your policy may give more)
Time to collect full replacement cost
- What it gives you
- At least 36 months from the first actual cash value payment, plus six-month extensions for good cause
- Source
- Insurance Code §2051.5
Additional living expenses
- What it gives you
- At least 24 months, plus up to 12 more for delays beyond your control
- Source
- Insurance Code §2060
Contents after a total loss
- What it gives you
- An offer of at least 60% of your contents limit, up to $350,000, without an itemized inventory, for a furnished primary home
- Source
- Insurance Code §10103.7
| Rule | What it gives you | Source |
|---|---|---|
| Time to collect full replacement cost | At least 36 months from the first actual cash value payment, plus six-month extensions for good cause | Insurance Code §2051.5 |
| Additional living expenses | At least 24 months, plus up to 12 more for delays beyond your control | Insurance Code §2060 |
| Contents after a total loss | An offer of at least 60% of your contents limit, up to $350,000, without an itemized inventory, for a furnished primary home | Insurance Code §10103.7 |
Claim questions can also go to the California Department of Insurance (opens in a new tab) consumer line at 800-927-4357.
What else does a Ventura home need besides fire coverage?
Short answer
Flood and earthquake coverage, which standard homeowners policies exclude. The city has rivers on two sides and a long beachfront, and like the rest of coastal Southern California it is earthquake country.
The Santa Clara River forms the southern edge of town, and on the west side the county is planning repairs to the Ventura River levee after a 2008 FEMA review found it fell short of federal certification standards. NFIP flood policies typically take 30 days to start, so buy before the rainy season.
Earthquake needs its own policy, through the California Earthquake Authority or a private insurer; see our earthquake insurance page. Near Pierpont and the Keys, salt air corrodes fixtures and railings. That counts as maintenance, which homeowners policies exclude as wear and tear.
What if your insurer won't renew a hillside home?
Short answer
Shop right away. Mercury and Travelers are our first calls; when no standard carrier will take the home, the California FAIR Plan can insure it against fire and a difference-in-conditions (DIC) policy can add the coverage the FAIR Plan leaves out.
Our guide to a home insurance non-renewal in California explains what to do next, the California FAIR Plan guide explains the pairing, and our wildfire and home insurance guide, written for Santa Clarita, applies to most hillside homes.
Underwriters often ask about roof age, vents, wiring and plumbing updates and brush clearance, so have those answers ready. You sign by e-signature, with no trip to Valencia.
To insure the cars too, see car insurance in Ventura, or the Ventura area page for renters, landlords and businesses. We also quote home insurance in Santa Clarita, home insurance in Palmdale and home insurance in Orange County; the statewide basics are on our California homeowners insurance page.
Sources we used for this page (11)
- 1CAL FIRE: Thomas Fire incident summary (opens in a new tab)fire.ca.gov
- 2Ventura County Star: Eight years after the Thomas Fire, some return home (December 2025) (opens in a new tab)yahoo.com
- 3CalRecycle: Thomas Fire cleanup complete, 263,925 tons cleared from 672 properties (June 2018) (opens in a new tab)calrecycle.ca.gov
- 4Ventura Breeze: Ventura Fire Department releases updated fire hazard severity zone maps (April 2025) (opens in a new tab)venturabreeze.com
- 5California Insurance Code §10102: residential property insurance disclosure (opens in a new tab)leginfo.legislature.ca.gov
- 6California Insurance Code §10103: building code upgrade coverage (opens in a new tab)leginfo.legislature.ca.gov
- 7California Insurance Code §2051.5: time to collect replacement cost (opens in a new tab)leginfo.legislature.ca.gov
- 8California Insurance Code §2060: additional living expenses (opens in a new tab)leginfo.legislature.ca.gov
- 9California Insurance Code §10103.7: contents payments after a total loss (opens in a new tab)leginfo.legislature.ca.gov
- 10FEMA: Flood insurance (opens in a new tab)fema.gov
- 11Ventura County Public Works: Ventura River (VR-1) levee rehabilitation project (opens in a new tab)publicworks.venturacounty.gov
Ventura
Also in Ventura
Other areas we serve
Home insurance in other cities
Questions we hear a lot
Home insurance in Ventura: common questions
Short answers to what people ask us most. Anything else, call and ask Brian or Dolores.
Still have a question?
Talk to a licensed agent at the Valencia office.
(818) 909-7486Mon to Fri, 9 AM to 4 PM
Can I still get home insurance in Ventura's hillside neighborhoods?
Often, yes, though some homes take more shopping. Underwriters weigh the fire hazard zone, roof, vents, brush clearance and claims history, so mention recent upgrades. If no standard carrier will write the house, the FAIR Plan plus a difference-in-conditions policy is the fallback, and we keep checking the market at each renewal.
My home was rebuilt after the Thomas Fire. Should my coverage change?
It should at least be reviewed. A rebuilt house is usually newer, sometimes larger and built to current codes, so a dwelling limit set before the fire may not match today's replacement cost. Send us the final square footage, roof type and new features, and we will check the limit and how each carrier views the new construction.
Does homeowners insurance cover smoke damage from a wildfire?
Usually, yes. Fire and smoke are covered causes of loss in most homeowners policies, so soot damage to walls, furnishings and the heating and cooling system can be part of a claim even if flames never reached the house. Photograph everything, keep cleaning receipts and report the claim promptly. Details depend on your policy.
Is flood insurance worth it near the beach or the Ventura River?
For many coastal and river-adjacent homes, it deserves a close look. Check the address on FEMA's flood maps: in a high-risk zone with a government-backed mortgage, flood insurance is required. Elsewhere it is optional, but homeowners policies still exclude flood, and NFIP coverage usually starts 30 days after you buy it.
Can you insure a rental house or condo near the coast?
Yes. For a rental house or duplex we can quote landlord coverage through carriers such as Steadily or Obie, which insures the building and your landlord liability, not tenants' belongings. Condo owners need an HO-6 policy matched to the HOA's master policy. See our landlord insurance page or the condo insurance page for details.
Keep reading
Related coverage
Home insurance
Homeowners insurance for California houses, quoted with carriers like Mercury and Travelers by a family-run independent agency in Valencia.
Learn more
Earthquake insurance
Separate earthquake coverage for California homes, condos and renters, with help comparing CEA and private policy options.
Learn moreCalifornia FAIR Plan guide
The California FAIR Plan is where a house goes when regular insurers say no.
Learn more
Got a home insurance non-renewal?
A non-renewal letter means your insurer won't offer you another term when this policy ends.
Learn more
Free quote · No obligation
Get a free home insurance quote in Ventura
Tell us what you want to insure and Brian will compare carriers, then we'll call you back. Everything happens by phone, email and e-signature, so there's no need to drive to Valencia.
- Mon to Fri, 9 AM to 4 PM. During business hours we usually call back within the hour.
- CA License #0D44425 · 30 years of experience